Auction Channel Just Printed Its First Hard Fail — Gramercy Park Seized Unit Underbids by 1.8%
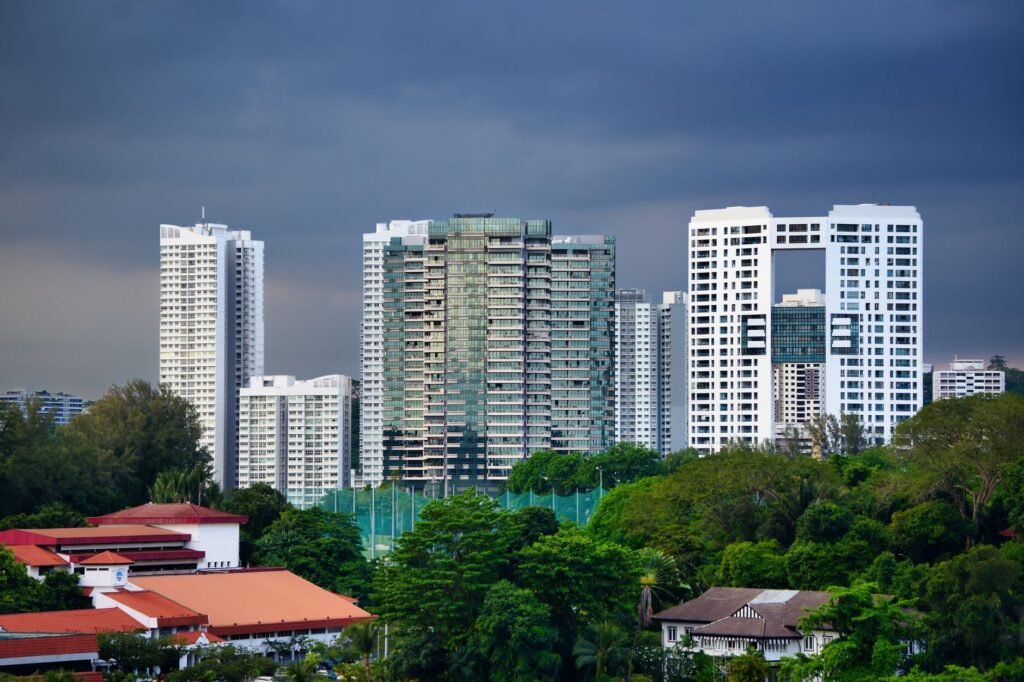
Business Times reported yesterday that a 1,292 sq ft two-bedroom-plus-study at Gramercy Park — guide price S$3.82 million, marketed by SRI — drew a highest bid of S$3.75 million and failed to clear. A 1.8% gap between vendor opening and best on-the-day bid is the kind of result that tells us less about this specific unit than about the price-discovery machinery now running through prime CCR stock. We have covered the announcement phase of the seized-property auctions across four prior digests (3, 8, 11 and 16 September); EdgeProp’s headline then was the upcoming 23 September SRI auction of six Martin Modern units (guide S$2.238M–S$4.98M) and four Wallich Residence units (guide S$4.42M–S$6.78M). The Gramercy Park result is the first one in the pipeline that actually went to the hammer and bounced.
The clean read for residential readers. The forced-sale channel is real, but the auctioneer’s opening guide is not a guaranteed clearing price. For owners of comparable prime leasehold stock, this is the first 2026 data point that says your “what-if-I-had-to-liquidate-tomorrow” print could come in 1–2% below your private-listing ask. For cash buyers, it confirms genuine discount room exists — but you need to bid, not assume the unit will come to you. Combine that with EdgeProp’s recent “Landed homes for S$880,000” affordability piece and the co-living capital rotation (BT, 16 Sep) reshaping the rental comp set for 1- and 2-bedder CCR units specifically, and the same conclusion keeps appearing: the S$3M–S$7M CCR leasehold tier is the softest pocket in the market right now, and the auction channel is just the first place that conclusion has been price-tested.
Source: Business Times — Luxury properties seized in S$3 billion money laundering case fail to sell at auction (17 Sep). Note: bid figures from BT paywalled report — verify against SRI auction-house records and URA caveat portal before client citation. Gramercy Park is a 99-year leasehold (commonly misreported as freehold) — confirm tenure before any comp.
🏘️ HDB
No new stories today.
🏙️ Private Residential
- Belgravia Ace lands its TOP, with Tong Eng launching the final 15–20 freehold strata semi-detached homes in District 28. Built-up 3,929–4,370 sqft, 3 storeys + basement + attic, on a 26,000 sqm site. Why this matters: the final tranche of a long-running D28 landed-strata project is a useful price-discovery data point for anyone benchmarking against the new EC pipeline in the same corridor. ERA Singapore via Facebook.
🏡 Landed Residential
- Oei Tiong Ham Park area GCB sells for S$31.3M (~S$2,089 psf on 14,982 sqft freehold) — the Aug 19 BT print sits below the recent D11/Nassim band (S$2,415–S$4,550 psf) but tracks the Bishopsgate Sep 4 S$2,481 psf and the Q2 2026 GCBActually average near S$2,341 psf. Why this matters: a clean mid-cluster GCB print at S$2,000+ psf confirms the “S$2,000 psf is the new middle” framing for prime District 10/11 bungalows — scarcity, not volume, doing the pricing work. Business Times — Oei Tiong Ham Park area GCB sold for S$31.3 million. Note: 30-day-old print; psf from BT — verify against URA caveat portal.
- EdgeProp: landed homes at S$880,000 — what’s the catch? A useful affordability-tour piece surveying low-end landed rentals (Jalan Asas terrace and semi-D in D26 Mandai, S$5,500–S$7,300/month) against the new S$5M entry-level inter-terrace benchmark highlighted in recent landed commentary. Why this matters: the spread between rental yields on entry-level landed (where the gap is widest) and the new S$5M entry-price benchmark is where the “should I upgrade from condo to terrace” calculation actually lives. EdgeProp — Landed homes for $880,000.
📊 Wider Market (what it means for homebuyers)
- Institutional co-living capital broadening as conversion pathways get clearer (BT, 16 Sep) — the read-through for residential readers is the same one we flagged in July: more build-to-rent and co-living supply in the city-fringe 1- and 2-bedder segment will keep rental yields compressed over the next 2–3 years. For owner-occupiers, that means lease-renewal comps stay soft; for investors holding small CCR units, it means the rental income line is the variable to watch in any 2026 exit decision. Business Times — Making room for co-living in Singapore as investors commit, demand broadens.
_Stories: 4 new today (Private 1, Landed 2, Wider Market 1, HDB none). Sources: Business Times (Gramercy Park auction failure 17 Sep, Oei Tiong Ham GCB 19 Aug, co-living 16 Sep — paywalled, headlines + teasers only, paraphrased), EdgeProp (S$880K landed affordability — paraphrased), ERA Singapore (Belgravia Ace TOP — Facebook post, paraphrased). Auction underbid figure (S$3.75M vs S$3.82M guide) is from BT paywalled coverage — verify against SRI auction records and URA caveat before client citation. Oei Tiong Ham psf is a 30-day-old BT print; verify against URA caveat portal. Gramercy Park tenure correction note: 99-year leasehold, not freehold as some secondary coverage frames it._
Quick Self-Check
Click each question to reveal the answer.
What is the lead story in today’s digest?
The lead story is today’s Singapore residential deep-dive — see the section above titled “Auction Channel Just Printed Its First Hard Fail — Gramercy Park Seized Unit Underbids by 1.8%” for the full analysis, what it means for home buyers, and the next 90-day signals to watch.
Where can I read the original sources?
Every story in the digest links out to its source (Business Times, EdgeProp, Straits Times, etc.). Each bullet ends with a link to the original article — never to syndicated copies.
How does SmartNest choose what to cover?
Each weekday we pick the single highest-SEO-value residential story across HDB, private residential, and landed — plus a tight roundup of the day’s other notable prints. Core categories get full depth; the commercial/industrial wider-market section only fires when a story has a clear homebuyer read-through.